Medicare Made Simple
Easy and Simple Medicare Guide That Helps You Avoid Costly Mistakes. 100% Free Medicare Assistance From Kerwyn Jones.
Understanding Medicare
How We Help You
Medicare Made Simple
Free medicare consultations focused on what's right for you
Shop For Your Plans
We compare 30 + insurance carriers for you
No Hassle Enrollment
Simple process where we handle all the paperwork for you
Free Policy Service for Life
Our team assists with renewals and policy service for the life of your policy
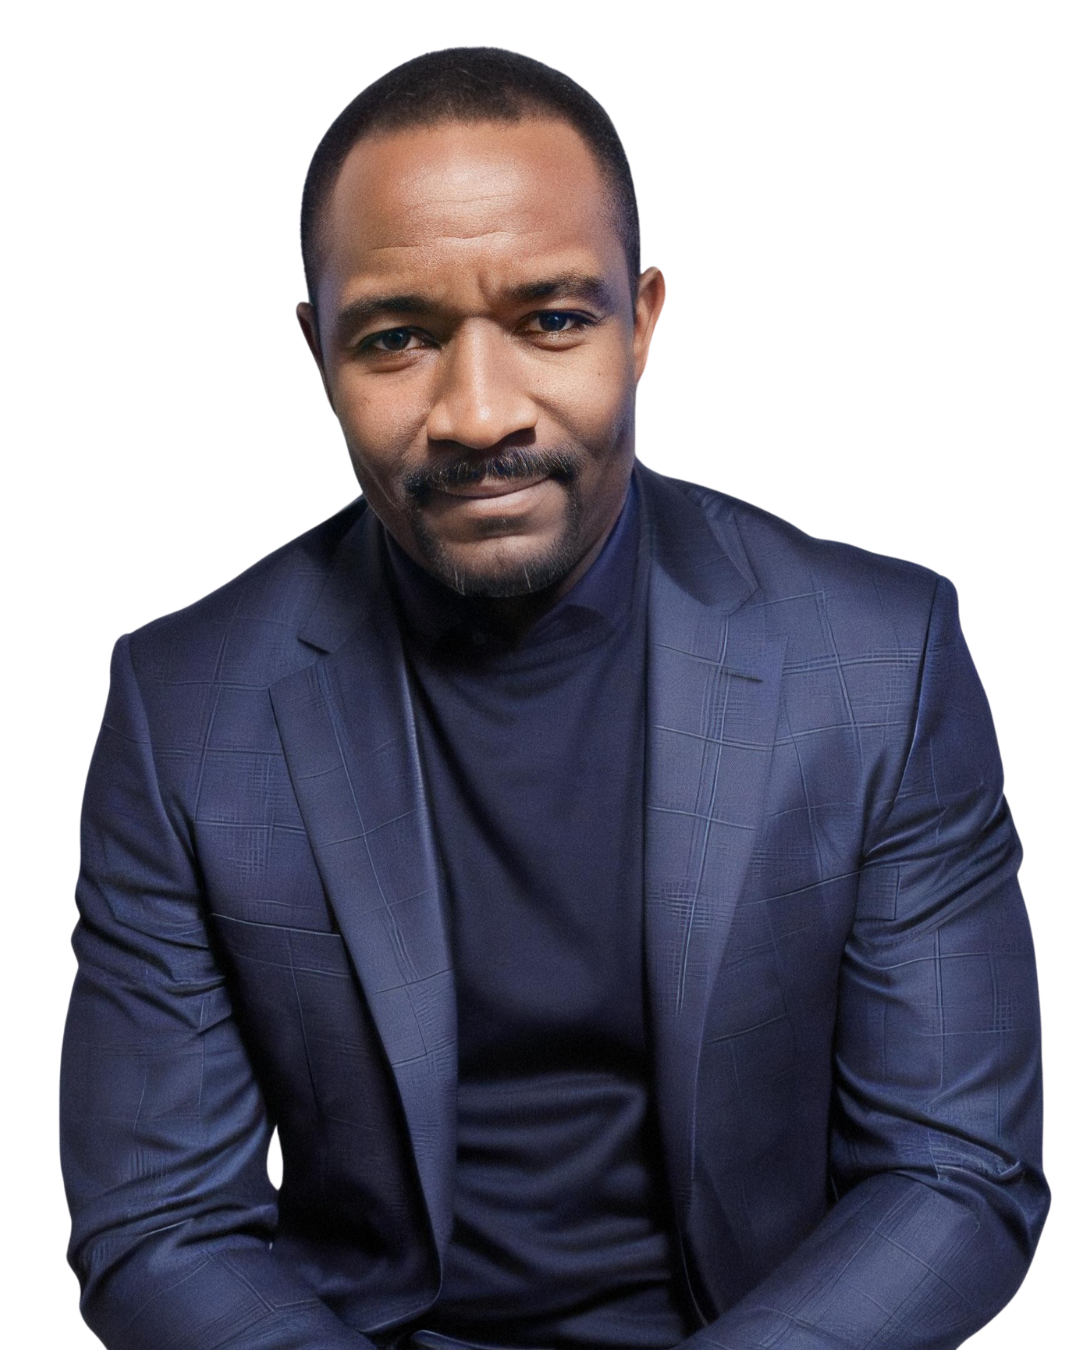
Experiene Peace of Mind With Kerwyn Jones
As your trusted insurance professional and founder of Jones Insurance Solutions, I help families get life insurance without medical exams to protect their home and income so there's no burden on their family.
My expertise in Medicare allows me to help seniors navigate the confusing process so they can enjoy their retirement.
Whether you're worried about leaving your family with unpaid mortgage bills and other living expenses if something happens to you, my mission is to help you get financial protection so your family can enjoy peace of mind when life takes an unexpected turn.
Call 321-415-7611Common Mistakes to Avoid
Why Clients Love Us?
Trusted Company
Our reputation for reliability and integrity makes us the go-to choice for life insurance and Medicare.
Guarantee Approval
Get the peace of mind knowing that you can get coverage without medical exams from our trusted insurance partners.
Flexible Pricing Plans
Customizable plans that fit your budget while offering comprehensive coverage.
24/7 Fast Support
Always available to assist you with any questions or concerns, no matter the time.
Medicare FAQ
Medicare has four parts. Part A is hospital insurance, covering inpatient hospital stays, skilled nursing facility care, hospice, and some home health care, and most people pay no premium for it. Part B is medical insurance, covering doctor visits, outpatient care, preventive services, and durable medical equipment, and it carries a monthly premium. Part C, also called Medicare Advantage, is an all-in-one alternative from private insurers that bundles Parts A and B and usually Part D, often with extra benefits. Part D is prescription drug coverage sold through private plans. Original Medicare is Parts A and B, and from there you can add Part D and a Medigap supplement, or choose a Part C plan instead.
It depends on how you prefer to get care and manage costs. Original Medicare with a Medigap supplement lets you see any provider that accepts Medicare nationwide and makes your out-of-pocket costs very predictable, but you pay a monthly supplement premium and buy Part D separately. Medicare Advantage often has a low or $0 premium and may include extras like dental, vision, and hearing, but you generally use a provider network and pay copays as you go. The right fit depends on your doctors, prescriptions, budget, and travel habits, which is exactly what a free review can help you compare.
Missing your enrollment window can lead to lasting penalties. For Part B, the penalty is generally an extra 10% added to your premium for each full 12-month period you were eligible but did not enroll, and it usually lasts as long as you have Part B. For Part D, a smaller amount is added to your drug premium based on how long you went without creditable coverage, and it also generally continues for as long as you have the plan. There are exceptions if you had qualifying coverage, such as from an employer. Because the rules are specific, it is worth reviewing your situation before a deadline passes.
It depends on your employer's size and your coverage. If you work for a larger employer (generally 20 or more employees) with creditable group coverage, you can often delay Part B without penalty and enroll later through a Special Enrollment Period when you retire. If your employer is small, Medicare may need to be your primary coverage, so enrolling on time matters. Many people still take premium-free Part A at 65 either way. It is a good idea to confirm how your specific plan coordinates with Medicare before deciding.
Original Medicare (Parts A and B) generally does not cover routine dental, vision, or hearing care such as cleanings, eyeglasses, or hearing aids, though it may cover certain medically necessary services. Many Medicare Advantage (Part C) plans do include these extras, and standalone dental or vision plans are also available. If these benefits are important to you, they are worth factoring into your plan choice.
Most people first enroll during their Initial Enrollment Period, a seven-month window that begins three months before the month you turn 65, includes your birthday month, and ends three months after. If you already receive Social Security, you may be enrolled in Parts A and B automatically; otherwise you sign up through the Social Security Administration online, by phone, or in person. From there you can add a Part D drug plan and either a Medigap supplement or a Medicare Advantage plan. Enrolling during this window helps you avoid late penalties.
Medicare is a federal health insurance program based mainly on age (65 and older) or certain disabilities, regardless of income. Medicaid is a joint federal and state program based on financial need that helps cover costs for people with limited income and resources. Some people qualify for both, known as being dually eligible, and the two programs then work together to cover more of their costs. Medicaid eligibility and benefits vary by state.
IRMAA stands for the Income-Related Monthly Adjustment Amount. If your income is above certain thresholds, you pay an extra amount added to your standard Part B and Part D premiums. Medicare bases this on your tax return from two years prior, so your income from two years ago can affect your premiums today. If your income has dropped due to a life event like retirement, you can ask Social Security to reconsider. Most people fall below the thresholds and are not affected.
Generally no, not for ongoing custodial care. Medicare may cover a short, medically necessary stay in a skilled nursing facility after a qualifying hospital stay, plus some home health and hospice care, but it does not pay for long-term custodial care such as everyday help in a nursing home or assisted living over the long run. Those costs are typically covered by long-term care insurance, personal savings, or Medicaid for those who qualify. Planning ahead for this gap is important.
The Medicare Annual Enrollment Period runs from October 15 to December 7 each year, with changes taking effect January 1. During this time you can switch between Original Medicare and Medicare Advantage, change or join a Part D drug plan, or move between Advantage plans. There is also a Medicare Advantage Open Enrollment Period from January 1 to March 31 for people already in an Advantage plan to make one change. Reviewing your plan each year is smart, since coverage, costs, and drug lists can change.
Part D is prescription drug coverage offered through private plans, either as a standalone plan added to Original Medicare or built into a Medicare Advantage plan. Each plan has its own list of covered drugs (a formulary), pharmacy network, premium, deductible, and copays, so the same medication can cost very different amounts from one plan to the next. The best way to choose is to compare plans based on your specific prescriptions and preferred pharmacy, which we can do with you at no cost. Plans can change each year, so it is worth reviewing yours during Annual Enrollment.
Get My Plan Started
Personalized, Free Life Insurance, Medicare and Health Insurance Assistance
We are not connected with or endorsed by the United States Government or the Federal Medicare Program. We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.