Life Insurance That Pays While You're Alive
Protect your income during a medical event while you're alive and leave money behind to cover final expenses when you die.
Living Benefits
Terminal Illness Payout
Cash payout to cover bills if you're diagnosed with a terminal illness.
Protects Your Income
Can't work due to a major medical illness? Your life insurance plan can supplement your income.
Critical Illness Payout
Cash payout covers the medical expense if you get a critical illness such as cancer, a stroke, or a heart attack.
Emergency Funds
Helps to cover emergency expenses when there is a major life event.
Easy Access
Grows in cash value and allows you with flexible access to your savings.
Tax-Free Money
Creates generational wealth via a cash payout to your family upon your death.
Why Clients Love Us?
Trusted Company
Our reputation for reliability and integrity makes us the go-to choice for life insurance and Medicare.
Guarantee Approval
Get the peace of mind knowing that you can get coverage without medical exams from our trusted insurance partners.
Flexible Pricing Plans
Customizable plans that fit your budget while offering comprehensive coverage.
24/7 Fast Support
Always available to assist you with any questions or concerns, no matter the time.
Life Insurance FAQ
Term life insurance covers you for a set period, such as 10, 20, or 30 years, and pays a death benefit only if you pass away during that term; it has no cash value and is usually the most affordable option. Whole life insurance is permanent, lasts your entire life as long as premiums are paid, and builds cash value you can borrow against over time. Term is often chosen to cover temporary needs like a mortgage or raising children, while whole life is used for lifelong coverage and building cash value. Many of the plans we offer also include living benefits you can use while you're still alive.
A common starting point is roughly 10 to 12 times your annual income, but the right amount depends on your situation: outstanding debts like a mortgage, the income your family would need to replace, future costs such as college, and any final expenses. The goal is enough coverage that your loved ones can keep their lifestyle and stay in their home if something happens to you. We can walk through your numbers and tailor the coverage to your budget.
In most cases, yes. Many conditions, such as controlled diabetes, high blood pressure, asthma, or a history of anxiety, are commonly accepted, sometimes at standard rates. More serious conditions may affect your options or pricing, and there are policies designed for people with significant health histories, including no-exam options. Because we work with several trusted insurance partners, we can match you with a carrier that views your health favorably.
Employer group coverage is a helpful benefit, but it is often not enough on its own. It is typically limited to one or two times your salary, usually ends if you leave or lose your job, and generally cannot go with you. An individual policy stays with you regardless of employment, lets you choose an amount that fits your family's needs, and locks in your rate. Many people keep their group coverage and add their own policy on top of it.
Not always. Many policies today offer no-exam underwriting, where you answer health questions instead of completing a physical, and coverage can often be approved quickly. Whether an exam is required depends on your age, the coverage amount, and the carrier. Helping families get life insurance without medical exams is a core part of what we do.
In most cases, yes. Life insurance death benefits are generally paid to your beneficiary free of income tax. There can be exceptions in specific situations, such as very large estates or certain ownership arrangements, so it is wise to confirm the details for your circumstances with a tax professional. This tax treatment is one of the reasons life insurance is such an efficient way to leave money to your family.
Your beneficiary is the person or people who receive the death benefit, and it can be a spouse, child, other relative, a trust, or a combination. You can name primary and backup (contingent) beneficiaries, and in almost all cases you can update them later as life changes, such as after a marriage, divorce, or new child. It is a good idea to review your beneficiary designations every few years to keep them current.
It often still makes sense. Buying while you are young and healthy locks in the lowest rates you are likely to ever qualify for, and that rate is protected even if your health changes later. A policy can cover debts a co-signer such as a parent would be left with, help with final expenses, and some plans build cash value or include living benefits you can use during your lifetime. If your responsibilities grow later, you will already have coverage in place at a price set when you were youngest and healthiest.
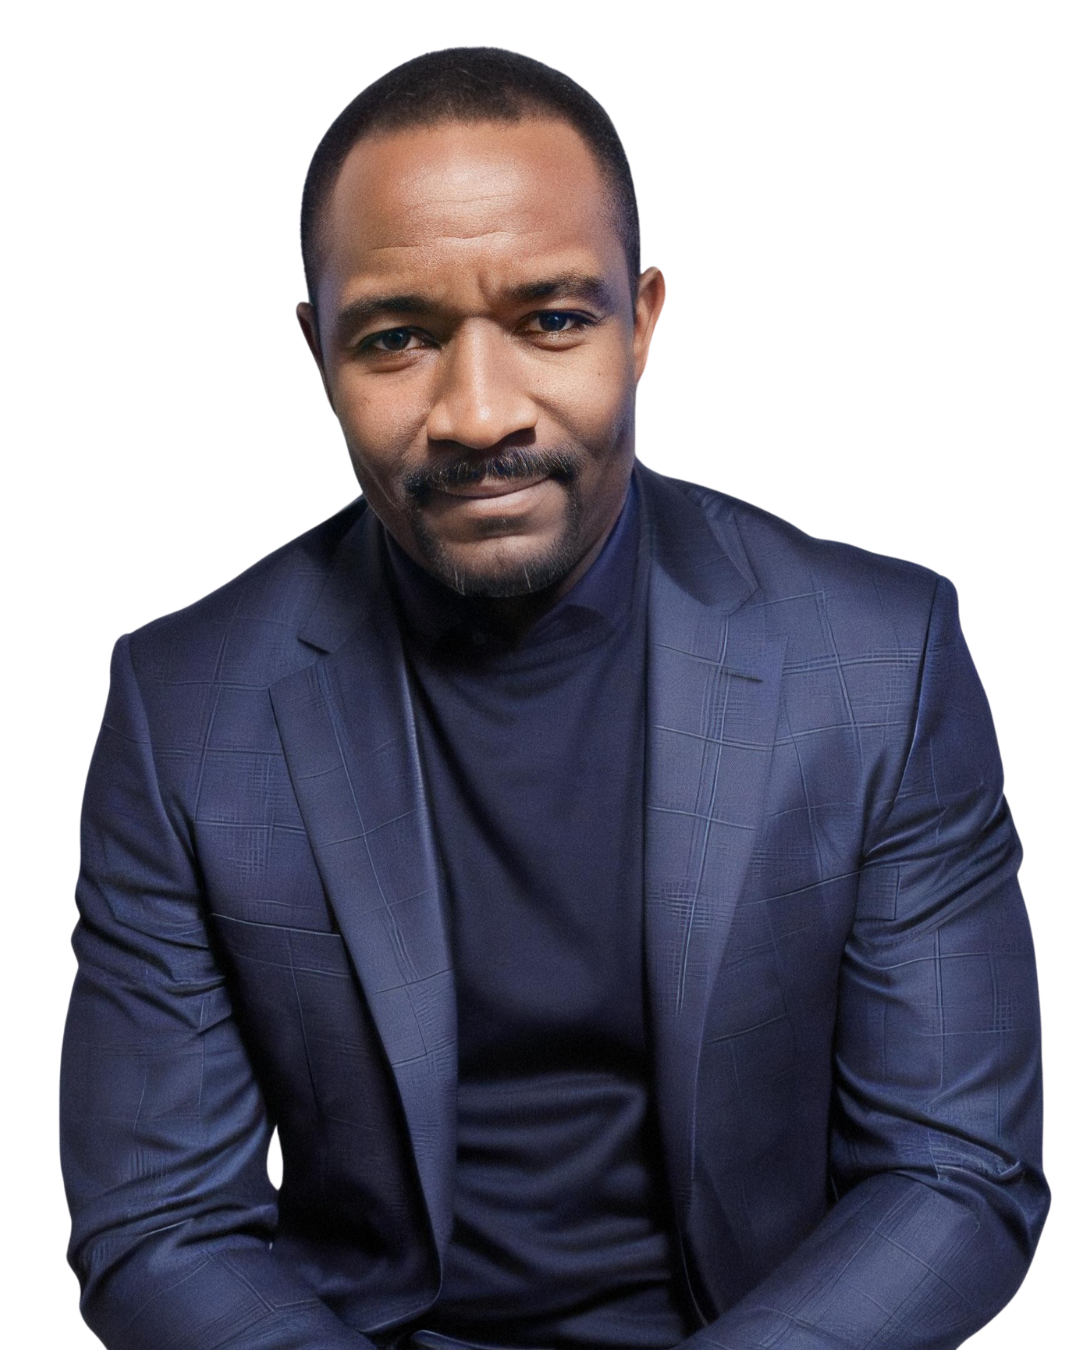
Experiene Peace of Mind With Kerwyn Jones
As your trusted insurance professional and founder of Jones Insurance Solutions, I help families get life insurance without medical exams to protect their home and income so there's no burden on their family.
My expertise in Medicare allows me to help seniors navigate the confusing process so they can enjoy their retirement.
Whether you're worried about leaving your family with unpaid mortgage bills and other living expenses if something happens to you, my mission is to help you get financial protection so your family can enjoy peace of mind when life takes an unexpected turn.
Call 321-415-7611Get My Plan Started
Personalized, Free Life Insurance, Medicare and Health Insurance Assistance